
Supply & Demand Metrics
1. Properties for Sale
● July 2024 → July 2025: +12.8%
● June 2025 → July 2025: +3.3%
● July 2025 vs. 6-year July average: +16.4%
2. New Listings
● July 2024 → July 2025: +19.2%
● June 2025 → July 2025: +14.8%
● July 2025 vs. 6-year July average: +3.3%
3. Sales Agreed
● July 2024 → July 2025: -9.8%
● June 2025 → July 2025: -19.3%
● July 2025 vs. 6-year July average: -14.8%
4. Price Changes
● July 2024 → July 2025: +11.8%
● June 2025 → July 2025: +18.8%
● July 2025 vs. 6-year July average: +40.7%
5. Withdrawn
● July 2024 → July 2025: -47.8%
● June 2025 → July 2025: -33.3%
● July 2025 vs. 6-year July average: -14.3%
6. Fall-Throughs
● July 2024 → July 2025: +320.0%
● June 2025 → July 2025: +110.0%
● July 2025 vs. 6-year July average: +50.0%
Asking Prices
7. New Listings Asking Price
● July 2024 → July 2025: +5.8%
● June 2025 → July 2025: +10.2%
8. Sales Agreed Asking Price
● July 2024 → July 2025: +9.5%
● June 2025 → July 2025: +0.5%
£ per Sq Ft
9. New Listings £/sq ft
● July 2024 → July 2025: -4.0%
● June 2025 → July 2025: -2.8%
10. Sales Agreed £/sq ft
● July 2024 → July 2025: +5.0%
● June 2025 → July 2025: +3.2%
The local housing market in SG6 closed out July 2025 with signs of renewed supply, pricing confidence, and a more cautious buyer pool. While activity levels remain respectable, we’re seeing a shift in tempo that reflects the broader recalibration of the market following the sharp rises and falls of recent years.
Stock Levels & New Instructions on the Rise
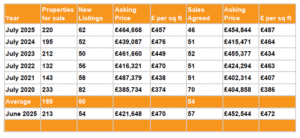
There were 220 homes available for sale, up 13% on July 2024 and 16% above the six-year average. This increase in stock comes alongside a 19% year-on-year rise in new listings, suggesting vendors are feeling more confident about testing the market, likely fuelled by recent pricing strength and stabilising mortgage rates.
Buyer Caution Evident in Sales Volumes
Despite the bump in supply, sales agreed fell by 9.8% compared with July 2024 and were down nearly 15% compared to the six-year July average. This suggests a gap between seller expectations and buyer willingness, with purchasers being more selective, possibly in response to rising fall-throughs and tighter affordability.
Pricing Trends: A Tale of Two Markets
Asking prices for new listings stood at £464,668, up 5.8% year-on-year, while sales agreed asking prices reached £454,844, a 9.5% increase from July 2024. Interestingly, while sellers are setting optimistic prices, sales are still being agreed at higher levels, suggesting that quality, well-priced homes are achieving strong results.
This pricing growth contrasts with a slight dip in £ per sq ft for new listings (down 4.0%) to £457, while sales agreed £ per sq ft rose 5.0% to £487. In essence, buyers are willing to pay more for the right home, but only if it represents value.
Market Friction: More Activity, More Volatility
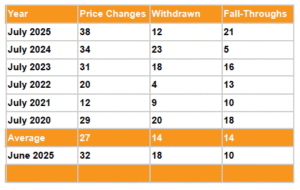
We saw 38 price changes in July, the highest in six years and 41% above the long-term average, reflecting sellers adjusting to market feedback. Withdrawals were down nearly 48%, which is a positive signal of seller commitment.
However, fall-throughs surged to 21, up dramatically from just 5 last year and well above the average of 14. This rise underlines how fragile some agreed sales have become, likely due to financing issues or tougher post-survey negotiations.
Summary: Balance Returning, But Not Without Caution
SG6 enters the second half of the year with a rebalanced market; supply is rising, sellers are engaging, and prices are holding. But the dip in agreed sales and the spike in fall-throughs suggests that buyer confidence still needs to firm up.
For homeowners thinking of selling, the message is clear: there is demand, but realism is essential. Correct pricing, strong presentation, and proactive negotiation will be key to securing a committed buyer in this market.